Risky Fiscal Leap: The Clash Between Nigeria’s 2026 Sugar Tax Proposals and Manufacturer Recovery
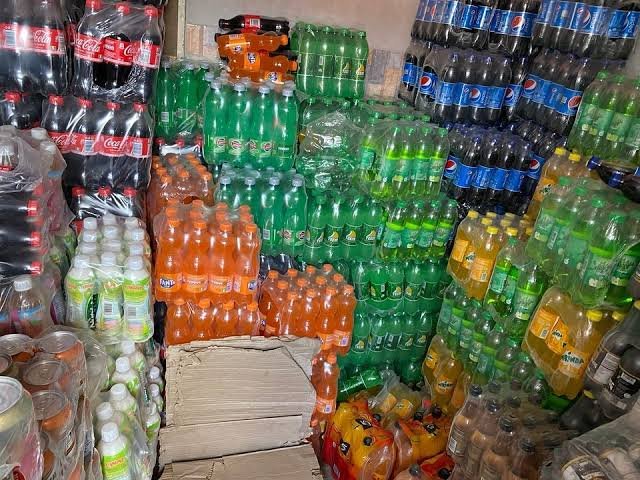
Against the backdrop of strong financial recoveries across Nigeria’s major food and agricultural producers in the first half of 2026, a high-stakes legislative battle threatens to upend the sector’s momentum. Even as industrial giants like Dangote Sugar and BUA Foods reported robust profit rebounds in H1 2026 through disciplined cost management, a new fiscal shock looms. The proposed amendment to the Customs, Excise Tariff, Etc. (Consolidation) Act (CETA) which passed its Third Reading in the Senate on June 4, 2026, and is currently before the House of Representatives, seeks to replace Nigeria’s existing fixed specific excise duty of N10 per litre on sugar-sweetened beverages (SSBs) with an ad valorem tax structure. According to Corporate Accountability and Public Participation Africa (CAPPA), this shift could skyrocket the effective tax burden to approximately N130 per litre based on prevailing retail prices. While proponents champion the reform as a necessary step to curb sugar consumption and boost healthcare financing, a policy research report by Africa Business Convention titled “Nigeria’s CETA Bill, Fiscal Policy, and Health Outcomes.” warns that the heavy fiscal shock threatens to penalize a manufacturing ecosystem just as it begins to stabilize. Flawed Design and Questionable Health Gains Beyond immediate manufacturing fallout, the structural framework of the proposed tax raises serious questions regarding policy coherence and public health efficacy: “SSB taxes reduce beverage purchases, but evidence of measurable reductions in obesity, diabetes, or hypertension at population level remains limited. In Nigeria, where sugar intake is already below WHO thresholds, the proposed amendment appears disproportionate to the strength of the health evidence,” ABC analyst highlighted in the report. Severe Economic Fallout: Output, Prices, and Jobs Layering an ad valorem jump to an effective N130 per litre on top of these structural realities introduces profound downside risks. Simulation models cited in the CAPPA and MAN submissions project severe adjustments if the policy is implemented in its current form: “The SSB sector is already adjusting to a constrained demand environment under the current tax, and further fiscal escalation would amplify existing pressures on output, employment, and investment. The proposed increase therefore represents a material downside risk to an industry that has not yet recovered to its pre-2022 performance levels.” The report notes. A Fragile Recovery: H1 2026 Financial Realities The timing of the proposed tax escalation intersects with a delicate period of financial adjustment for the nation’s sugar value chain. Major producers demonstrated profit recoveries in the first half of 2026 despite softer revenue volumes and moderated pricing driven by inflationary pressures: Despite these margin recoveries, historical data from the National Sugar Development Council (NSDC) underscores underlying sector vulnerability: total national sugar consumption fell 16% between 2022 and 2023, while domestic sugar production dropped 35% following initial macroeconomic pressures. A Call for Calibrated Policy With more than 133 million Nigerians living in multidimensional poverty and dealing with complex nutritional challenges, the expected health dividends of a blunt, heavy tax must be carefully weighed against broader socioeconomic realities. The report points out that before pushing forward with a steep fiscal escalation, policymakers should transparently review the performance and revenue utilization of the existing levy. If higher taxation is deemed essential, adopting a targeted, sugar-content-specific structure would offer a more balanced path protecting vulnerable households and hard-won manufacturing gains while providing genuine incentives for healthier product formulation.