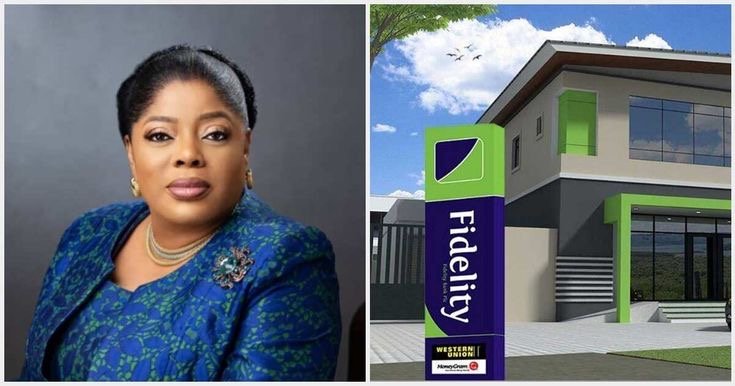
In a Nigerian banking sector still marked by abrupt exits and regulatory interventions, Fidelity Bank is managing something rarer: an orderly, internally driven succession. Nneka Onyeali-Ikpe, the first woman to lead the bank, is approaching the end of her tenure, which began in January 2021 and was extended by the Board to the end of 2026.
The exit is proceeding in accordance with the bank’s contractual terms and governance framework, well within the Central Bank of Nigeria’s maximum 12-year limit for bank Managing Directors. The Board has already completed its internal process and submitted its choice to the CBN; a public announcement will follow regulatory clearance. This approach mirrors the bank’s previous two chief executive transitions, both of which elevated serving Executive Directors. For investors watching Nigeria’s financial system, the interest lies less in the identity of the successor than in the predictability of the process itself.
Scale Under Onyeali-Ikpe
Her administration expanded the bank’s balance sheet by approximately 280%, from N2.758 trillion ($2.04 billion) at the end of 2020 to N10.46 trillion ($7.75 billion) by the end of 2025.The N10.46 trillion marked an 18.6% increase from N8.82 trillion a year earlier.
Customer deposits stood at N6.89 trillion ($5.10 billion), while total equity exceeded N1.09 trillion ($807 million). Gross earnings grew by 87.7% to N1.04 trillion in 2024 and expanded a further 45.6% to N1.52 trillion ($1.13 billion) in 2025. Although profit before tax rose 210% to N385.2 billion in 2024, it declined by 9.7% to N347.7 billion ($258 million) in 2025, primarily driven by unrealised mark-to-market losses on derivative positions. Meanwhile, the non-performing loan ratio improved to a healthy 2.4%.
Physical expansion was kept deliberately restrained. The network of business offices moved from roughly 250 at the start of her tenure to 255 by 2025–2026, featuring selective openings in locations such as Surulere, Kamba, Owerri-North, and Eket. This pattern aligns with a digital-first model prioritizing scalable channels and targeted physical presence over broad branch proliferation, even as the customer base surpassed nine million.
Two major milestones carry weight beyond Nigeria’s borders. Fidelity completed its recapitalisation ahead of specialized Central Bank deadlines for banks holding international authorisation, pushing eligible capital above N530 billion ($393 million) against the N500 billion minimum requirement. In October 2026, the bank fully repaid its $400 million Eurobond, issued in 2021 at 7.625% at maturity using internal resources. Additionally, it completed the acquisition of what is now Fidelity Bank UK, establishing a regulated operational presence in London.
The momentum carried into 2026. In the first quarter of the year, gross earnings rose 37.9% year-on-year to N434.9 billion, while total assets crossed N11.35 trillion, up from N10.46 trillion at the end of 2025. Customer deposits increased to N7.38 trillion and total equity rose to N1.39 trillion. Profit before tax stood at N92.5 billion, lower than the corresponding period of 2025, reflecting a more normalised earnings environment after the exceptional gains of the prior year. The figures confirmed that the balance-sheet expansion under Onyeali-Ikpe continued into her final year in office.
Reflecting on the broader ecosystem, Onyeali-Ikpe noted in Lagos that: “At Fidelity Bank, we understand the role financial institutions must play in building this ecosystem. Our participation… reflects our commitment to helping creative entrepreneurs transform their talents into sustainable businesses that can compete successfully in local and international markets.”
A Stable Internal Model
The succession architecture has remained consistent over the years. In 2013–2014, the Board selected Nnamdi Okonkwo, then an Executive Director to succeed Reginald Ihejiahi. In 2020, it named Onyeali-Ikpe, who joined the Board as Executive Director for Lagos and the South-West in 2015, as Managing Director Designate; Central Bank approval was secured ahead of her assumption of office on January 1, 2021.
The current exercise follows this exact sequence: the Board Remuneration, Nomination and Governance Committee leads identification and recommendation, external evaluation is typically utilised, the Board approves, and final appointment requires Central Bank clearance under the Approved Persons Regime. The bank’s succession planning policy was formally reviewed in 2024.
In a clarifying statement at its 38th Annual General Meeting, held on 9 October 2026, the commercial bank which is publicly listed on the Nigerian Exchange Limited confirmed that “the relevant succession decision has been submitted to the Central Bank of Nigeria for regulatory consideration” and dismissed claims of external influence as unfounded.
This preference for internal candidates is structural. Both Okonkwo and Onyeali-Ikpe were elevated from the Executive Director cadre after multi-year tenures, showcasing a robust talent pipeline. In September 2025, the Central Bank issued guidance to Domestic Systemically Important Banks requiring regulatory approval for a successor Managing Director at least six months before an incumbent’s tenure expires, alongside a public announcement at least three months prior. Fidelity’s timeline strictly adheres to these requirements.
Defining the Next Phase
The incoming chief executive inherits a larger balance sheet, a cleaner loan book, a UK subsidiary, and proven capacity to meet significant foreign-currency obligations through internal liquidity. However, the competitive landscape has shifted. With most major Nigerian banks having cleared the new capital thresholds, future gains will rely less on balance-sheet expansion and more on execution: the economics of the London franchise, deposit competition in a post-recapitalisation market, and the ability to convert digital scale into sustained risk-adjusted returns without overextending the selective physical footprint.
In a financial system where leadership changes have historically sparked uncertainty, Fidelity’s record of two consecutive Board-driven internal handovers stands out. Whether the next Managing Director can translate that institutional continuity into ongoing competitive advantage remains the principal test though the bank’s history indicates it will continue looking first to its own bench.
(Note: USD equivalents are approximate, based on the CBN NFEM rate of N1,350/$ at the time of writing.)